Corporate Travel Tax Recovery & Advisory

GST/HST recovery on airline tickets, hotel stays and employee travel expenses.

Quadcan helps corporate finance and tax teams identify potentially overlooked input tax credits arising from travel and employee expenses.

Combining extensive airline distribution experience, transaction-level data analysis and technology-enabled tax classification, we help organizations review historical expenditures, identify potential recovery opportunities and strengthen their indirect-tax compliance processes.

Estimate Recovery See how it works

For CFOs, Controllers and Directors of Finance at mid-size and large Canadian organizations.

E-TICKET · YYZ → YVR ECONOMY · ONE WAY
—Base fare412.00taxable YRCarrier surcharge48.00taxable CAAir Travellers Security Charge9.46taxable SQAirport improvement fee40.00taxable RCHST 13% (ON)66.23ITC
TOTAL CAD575.69
Expense report sees
$575.69 · tax field blank
Recoverable ITC
$66.23
Illustrative ticket. Amounts for demonstration only.

Recovery estimator

Estimate your recovery in under a minute.

Enter approximate annual travel spend, tax included. The estimate updates as you type.

NoneAll of it
Estimated recovery · 4 years
—
Sales tax paid on travel / yr
—
Eligible after meals 50% limit / yr
—
Potentially unclaimed / yr
—
Get a detailed assessment

Indicative only. Assumes amounts include tax and are incurred in the selected province; international airfare is excluded as generally zero-rated. The range reflects eligibility verification and supporting documentation. Not tax advice.

Travel is where input tax credits leak — in both directions.

Under-claiming leaves cash with the CRA. Over-claiming GST/HST on zero-rated or non-taxable charges creates reassessment exposure. Most finance teams can't see either, because the detail lives in ticket and folio data, not in the expense report.

01

Totals-only capture

Card feeds and expense tools record the amount paid. The GST, HST and QST embedded in it are never broken out, so the ITC is never claimed.

02

Zero-rated vs. taxable legs

International and transborder itineraries turn on continuous-journey and place-of-supply rules. Blanket coding claims tax that was never charged — or misses tax that was.

03

Fees nobody classifies

Seat, bag and change fees, TMC and agency service fees, hotel service charges and municipal accommodation taxes each carry their own treatment.

04

Documentation gaps

A claim is only as good as the supporting invoice. Missing supplier registration numbers and incomplete receipts turn valid ITCs into audit adjustments.

Our services

Travel tax recovery and indirect-tax support, from ticket to return.

Corporate travel GST/HST recovery assessments

A structured review of your organization’s travel spend to identify where GST/HST input tax credits may have been missed.

Airline ticket tax analysis and reconciliation

Ticket-level breakdown of fares, surcharges and tax codes, reconciled against what was recorded and claimed.

Historical expense and input tax credit reviews

Review of prior periods still open for claims across travel and employee expenses, with supporting schedules.

Indirect-tax data analytics

Transaction-level classification of travel and expense data to show where GST/HST, HST and QST arise.

CRA audit documentation and reconciliation support

Reconstruction of the trail from source document to return line, to support your team or adviser in an audit.

Not sure where to start? Get an indicative range from your annual travel spend. Estimate Recovery →

Our work complements existing finance teams and external tax advisers. Identified recovery opportunities are subject to eligibility verification and supporting documentation.

How it works

From data export to filing-ready schedules. No system access required.

  1. Step 1

    Intake

    You share exports you already have: TMC reports, corporate card statements, expense platform data, hotel folios.

  2. Step 2

    Ticket-level classification

    Each ticket is rebuilt into its fare, surcharges and tax codes, and each leg is classified by journey type and place of supply.

  3. Step 3

    Reconciliation

    Findings are matched against what was claimed, separating unclaimed credits from over-claims and documentation gaps.

  4. Step 4

    Working papers

    You receive period-by-period schedules with source references, ready for your tax team or adviser to file and defend.

What we review

The whole trip, not just the airfare.

GST, HST and QST across every province, with the line items that typical expense coding misses.

Category Line items we classify Where it typically goes wrong
Air Base fare, carrier surcharges, Air Travellers Security Charge, airport improvement fees, seat, bag and change fees Domestic, transborder and international legs coded the same way
Hotel Room, service and resort fees, municipal accommodation tax, incidentals on the folio Folio taxes claimed as one line; meals on the folio not separated
Ground & rail Rail, car rental and its levies, ride-hailing, parking Receipts without supplier registration numbers
Agency & TMC fees Booking, service and change fees from your travel management company Fees buried in the ticket total or on a separate invoice nobody codes
Meals & allowances Meals and entertainment, per diems and reasonable travel allowances The 50% restriction misapplied; allowance ITCs not claimed at all

For advisory and indirect tax firms

Bring in airline expertise on the travel line of your engagement.

Commodity tax and recovery-audit practices see travel in nearly every engagement, but airline ticketing data is its own language. We work under your engagement, return schedules in your format, and never contact your client without you.

Discuss a partnership →
  • Subcontract or referral — whichever model fits your engagement letter
  • Ticket-level working papers your reviewers can trace line by line
  • Your client relationship stays yours — white-label deliverables on request

Why Quadcan

Built by people who issue airline tickets — and understand the tax on them.

Most recovery reviews are run by tax generalists reading expense reports. Quadcan reads the ticket itself: the fare construction, the tax codes, the GDS record behind it. That's the difference between an estimate and a defensible claim.

Travel industry
Founding and running travel services and technology businesses since 2012
Tax advisory
SR&ED specialist, KPMG
Airline distribution
GDS systems, ticketing, fare structures and airline tax codes
Consulting
Oracle and IBM
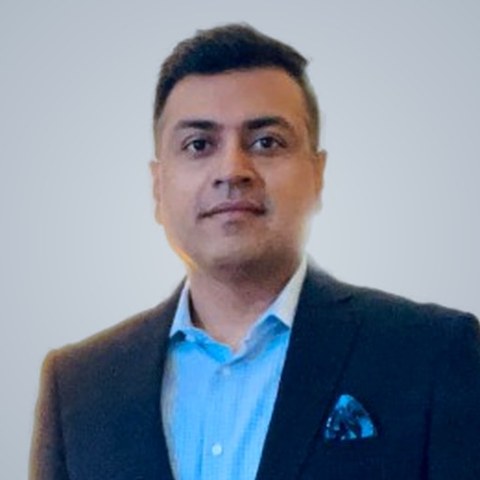
Vibhor Chhabra

Vibhor Chhabra

Travel Industry Tax & Technology Consultant

  • Corporate Travel
  • GST/HST Recovery
  • Indirect Tax Analytics
  • Airline Distribution

Professional focus

Helping Canadian corporations, accounting firms and tax advisory practices navigate the complexities of travel-related taxation through industry expertise, structured analysis and practical technology solutions.

Vibhor Chhabra is a Canadian business and tax recovery consultant with over 20 years of experience spanning business and consulting, corporate travel and analytics.

He holds an MBA in Finance from the Schulich School of Business. His professional background includes roles with Oracle, IBM and KPMG, where he worked as a SR&ED specialist.

Since 2012, Vibhor has founded and managed businesses in travel services and technology, developing extensive knowledge of airline distribution and systems, ticketing processes, fare structures, airline tax codes and corporate travel operations.

Through Quadcan, he focuses on corporate travel expense analysis, GST/HST input tax credit (ITC) recovery opportunities, indirect-tax compliance and CRA audit support.

His work combines specialized airline transaction knowledge with technology-enabled analysis to help organizations identify potential tax recoveries, reconcile complex travel expenses, improve documentation and strengthen financial controls.

Areas of expertise

  • Corporate travel GST/HST and ITC recovery analysis
  • Airline ticket taxation and GDS transaction analysis
  • Travel expense reconciliation and compliance
  • Indirect-tax data analytics and automation
  • CRA audit documentation and support
  • Business process improvement and technology consulting

Questions finance teams ask

How far back can we recover?

Generally up to four years from the due date of the return in which the ITC could first have been claimed. Some large businesses and financial institutions have a shorter window; we confirm yours at the outset.

Do you need access to our systems?

No. We work from exports you already produce — TMC reports, card statements and expense data — under NDA.

Who files the claim?

Your tax team or external adviser. We deliver the analysis and supporting schedules; the filing decision stays with you.

What if the review finds over-claims?

We report them alongside the recoveries, so you can correct exposure on your terms rather than in an audit.

Find out where recovery opportunities may exist.

+1 647-863-4210 Toronto, Ontario